 English
 日本語
 عربى
 Español

-
 01
The Same Foil Tray, Four Different Purchase Orders
Industry News-Aluminum foil containers are a rare category where the product itself is almost identical everywhere, while the purchasing conversation changes almost entirely from one market to the next. The container that leaves a factory in Zhejiang or Gujarat is the same gauge, the same alloy, roughly the same rim. What differs is the word on the inquiry, the specification attached to it, and the reason a buyer is asking at all.
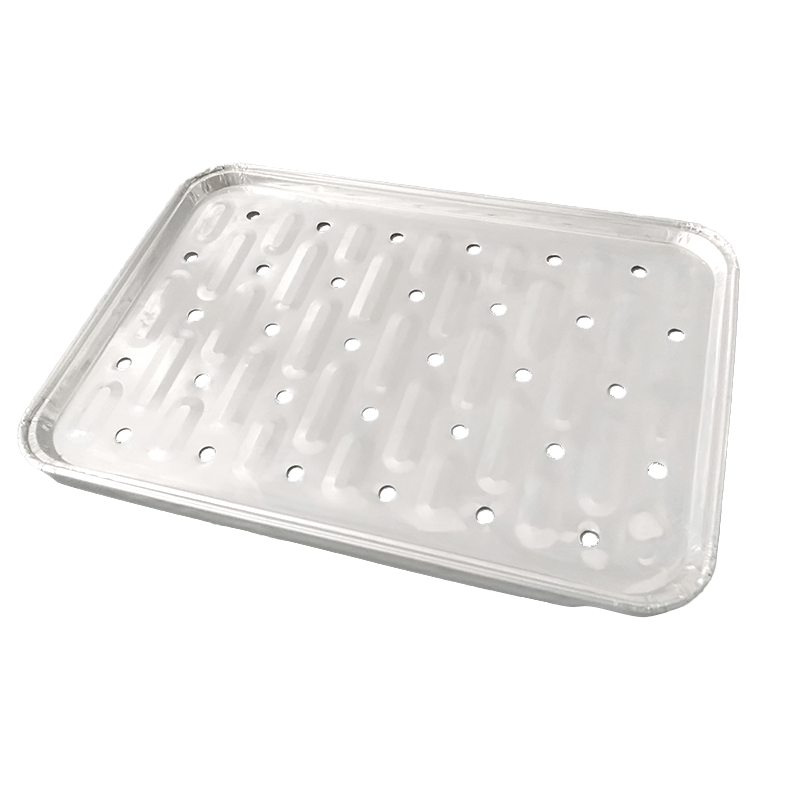
A cloud kitchen operator in Pune asks for a 450 ml Aluminium Foil Food Container. A US foodservice distributor orders a Full Size Pan, 3⅜ inches deep, without using the word “container” once. A banquet supplier in Riyadh wants صينية ألمنيوم ذهبية—golden trays—for a wedding season delivery. A Japanese airline catering buyer specifies 機内食トレイ and cares less about the alloy than whether the rim survives blast chilling without warping.
These are not translation variants of the same request. They are four different procurement problems. The global aluminum foil container market was valued at roughly USD 3.82 billion in 2025 and is forecast to reach USD 4.79 billion by 2030, growing at about 4.6% CAGR. But the growth is not evenly distributed, and the reasons behind it are not interchangeable. Below, a market-by-market look at what buyers are actually asking for—and why.
Content
- 1 India: Aluminium Foil Food Container—the purchase order got professionalized
- 2 United States: Full Size Pan / Half Size Pan—the regulation writes the specification
- 3 Middle East: صينية ألمنيوم—gold is not decoration, it is a specification
- 4 Japan: アルミホイル弁当箱 / 機内食トレイ—a declining import number that hides a stable operation
India: Aluminium Foil Food Container—the purchase order got professionalized
India’s foil container demand is usually described as a “food delivery story.” That is true but imprecise. The more useful way to read it is that packaging procurement itself has been professionalized, and foil containers are one of the formats that benefit.
India’s online food delivery market reached USD 12.3 billion in 2025, growing at roughly 18.5% CAGR, according to RedSeer data cited by packaging compliance platform Pakka. The cloud kitchen segment alone was estimated at USD 1.24 billion in 2025, projected to reach USD 3.69 billion by 2034 at a 12.28% CAGR. That growth has changed how packaging is bought. Cloud kitchen chains and aggregator-linked brands are moving from ad-hoc local purchases to standardized, repeat-order supply, which favors formats that can be specified by capacity and shape and reordered without renegotiation.
GEP Research estimates India’s foil and film container packaging market at about USD 1.87 billion in 2025, up 12.3% year on year, with aluminum foil substrate accounting for over 72% of output. Takeaway containers alone accounted for 43% of total demand, and the country’s chain restaurant count crossed 28,000 in 2025, with per-store foil container consumption rising from about 120 pieces per day to 155. That last number is the one worth watching. It tells you the growth is not only coming from new restaurants opening. It is coming from existing outlets using more foil per store as delivery volumes rise and packaging standards tighten.
The local B2B term is Aluminium Foil Food Container, transacted with capacity attached: 450 ml, 600 ml, rectangular, with paper or aluminum lid options. A 450 ml rectangular half-curl container is a workhorse SKU because it maps onto individual meal portions, biryani, curries and takeaway sets. The regulatory layer matters here too. India’s single-use plastic ban, effective July 2022, prohibits plastic plates, trays, cutlery and polystyrene containers for food service, and FSSAI’s packaging regulations list aluminum foil under IS 8970 as an allowed food-contact material. For a buyer, that means foil is not just a preference. It is a compliant default.
For suppliers, the search phrases that carry channel context are Aluminium Foil Food Container supplier for cloud kitchen and bulk foil containers India wholesale. “Foil container India” on its own is too broad to attract the buyer who is specifying a supply program rather than placing a one-off order.
United States: Full Size Pan / Half Size Pan—the regulation writes the specification
US foodservice buyers do not shop by “container.” They shop by steam table format, because the pan has to fit a chafing dish, a prep table opening, or a catering rack that already exists in the kitchen.
A Full Size Pan measures roughly 20¾ × 12¾ inches at the rim and holds between 7 and 11 quarts depending on depth. A 3⅜-inch-deep full-size pan runs about 343 fluid ounces, or roughly 10 quarts. A Half Size Pan is about 12¾ × 10⅜ inches, with capacity varying by depth. Depth names are not standardized across manufacturers. One supplier’s “deep” half pan is another’s “medium.” This is why US-facing product pages that only say “deep” without publishing rim dimensions, depth in inches and fluid-ounce capacity create friction in the inquiry. The buyer cannot verify fit without those three numbers.
But the more consequential driver is regulatory. State-level PFAS restrictions are moving from proposed to effective on a fixed timetable. California’s Senate Bill 682, approved by the legislature in 2025 and signed into law, prohibits the sale or distribution of food packaging containing intentionally added PFAS starting January 1, 2028, and the ban explicitly covers rigid foil trays. Illinois’ HB2516 takes effect January 1, 2026, and similarly restricts intentionally added PFAS in food packaging, including rigid foil and other trays. At the federal level, the PFAS-Free Procurement Act was introduced in April 2025, targeting government procurement of PFAS-containing products.
The practical effect is that aluminum foil containers are not being sold in the US primarily as a “green alternative.” They are being specified because they do not contain the chemistry that state laws are beginning to restrict. A buyer replacing a coated paper or molded fiber container with foil is not making an environmental statement. They are closing a compliance gap before an effective date.
That shifts the keyword field. PFAS-free aluminum foil containers, full size foil pan dimensions, and aluminum steam table pan capacity carry more B2B intent than “eco-friendly” language. Specification and compliance, in that order, are what US foodservice buyers search with when they are building a purchase order.
Middle East: صينية ألمنيوم—gold is not decoration, it is a specification
In Arabic-language B2B and retail contexts, the foil container is usually called صينية ألمنيوم (aluminum tray) or صحن ألمنيوم (aluminum dish). The demand story, however, is not a simple extension of the takeaway growth narrative. It is tied to hospitality infrastructure and to a product variant that English-language supplier pages routinely under-serve: the golden foil container.
Golden aluminum foil trays have become a visible premium segment in the UAE, Saudi Arabia and Qatar, particularly in hotels, catering operations, banquets and high-end takeaway. The cultural logic is straightforward: gold is associated with celebration and hospitality, which makes a golden tray appropriate for weddings, Eid gatherings and corporate entertaining. The functional logic is less obvious but equally relevant. Gold-colored foil containers are often produced from thicker material and are positioned for oven and open-flame heating. Some formats are marketed for microwave use, though buyers should confirm the coating and supplier instructions rather than assuming microwave compatibility from the color alone.
Saudi Arabia’s food-contact compliance regime is the gate that suppliers cannot skip. Aluminum foil packaging falls under SFDA jurisdiction as a food-contact material and must move through SASO conformity assessment and SABER platform registration. The process typically involves an SFDA food-contact registration through a Saudi authorized representative, migration testing against GSO 1016 (covering overall migration, heavy-metal migration, aluminum migration and specific coating substances), and a PC certificate through SABER before shipment. Silicone-coated or high-temperature-ink foil containers require additional coating migration testing. Labeling must be in Arabic, with material grade, intended use, thickness and warnings specified.
For a Saudi importer, a supplier that mentions golden trays but cannot answer questions about SFDA registration, SABER PC/SC certificates and Arabic labeling is not yet a qualified supplier. The container may be correct. The paperwork is not.
The Arabic-side keywords that reflect this buying process are صينية ألمنيوم للطعام بالجملة and صينية ألمنيوم ذهبية. On the English side, golden aluminum foil containers Middle East supplier and foil containers for catering Saudi Arabia capture the buyer who is sourcing for hospitality rather than retail.
Japan: アルミホイル弁当箱 / 機内食トレイ—a declining import number that hides a stable operation
Japan is the market in this group where the headline data is most misleading if read in isolation. Japanese aluminum foil container imports declined between 2020 and 2024, with a CAGR of roughly -3.55%, and 2024 imports were estimated to fall 5.76% further. Read quickly, that looks like a shrinking market.
Read more carefully, it is a market where the consumer-facing volume is thin but the operational volume is persistent. Plastic bento boxes dominate Japanese convenience-store and supermarket meal shelves. The Japanese term アルミホイル弁当箱 exists, and some consumers casually call foil containers 銀箱, but foil is not a daily default for household food storage or casual takeaway in the way it is in India or the US. The volume sits in places consumers rarely see: airline catering trays (機内食トレイ), bakery and confectionery molds, restaurant-chain takeaway programs, and prepared-food trays moving through central kitchens.
This changes what a Japan-facing page should say. The pitch is not “replace plastic bento for eco-conscious consumers.” It is operational consistency: whether the container holds its ribbed shape after filling, how it stacks and nests in a commissary, how the rim performs through chill and reheat, and how precisely the lid interfaces without leakage or buckling. Japanese business-use buyers evaluate foil containers as production line components, not as consumer packaging. The keyword cluster reflects that: アルミホイル容器 業務用, アルミホイル弁当箱 テイクアウト 業務用, and 機内食トレイ アルミ.
Choose AiKang for Top-Quality
Aluminum Foil Products
Explore Our
Featured Products
Ningbo Aikang Aluminum Foil Technology Co., Ltd, based in Ningbo, produces eco-friendly disposable aluminum foil products. They prioritize quality and customer satisfaction, serving the global market with innovative packaging solutions.


Quick Links
Contact
-
 No. 5 Yongxing East Road, Fengshan Street, Yuyao City, Zhejiang Province, China
-
 Tel: +86-15867468784
-
 E-mail: [email protected]
Send Us A Message
